Article Contents:
Sales are growing, but do you know what is happening to profitability?
Sales are growing. Orders are coming in. The team is busy.
But is your profitability also improving?
Many SME founders understand their products, customers and operations very well. They know what is happening on the shop floor and can quickly get into a customer or delivery issue.
But when it comes to understanding the P&L, I have seen some founders hesitate.
Some feel that finance is not their area and leave the P&L to the accountant, auditor or finance team. As long as sales are growing and there is sufficient money to run the business, they may not feel the need to go deeper into the numbers.
The problem is that sales growth does not always lead to profitable growth.
Your sales can increase while your profitability comes down. Material cost may be increasing. Product mix may be changing. Outsourcing cost may have gone up. Capacity constraints may be creating additional costs. Some customers or products may be contributing much less than you believe.
Unless you look at the P&L regularly, many of these issues can remain hidden.
I have worked with several SME founders who are technocrats and initially were not comfortable with P&L. But when they started reviewing a simple P&L every month, within two to three months they became comfortable interpreting the numbers and asking the right questions.
A founder does not need to become a finance expert.
But as a business head, you need to understand what the numbers are telling you about your business.
That is where a simple monthly P&L review can become a powerful management practice, rather than merely an accounting requirement.
How can growing sales actually reduce your profitability?
Growing sales normally gives us confidence that the business is doing well.
But sales growth does not always improve profitability.
I experienced this in one of my client organisations. They are in the casting and machining business.
The company was not reviewing its P&L every month. P&L was largely seen as something the auditor prepared at the end of the financial year for statutory and tax purposes.
When we introduced a simple monthly P&L review, something interesting started becoming visible.
Sales volumes were increasing. Expenses did not show any major increase relative to sales. Yet the net profitability was not improving as expected.
We decided to go deeper into the numbers.
The company was supplying higher volumes to one of its customers. To meet this increased demand, a critical machine with a high machine-hour rate was getting fully utilised.
This created another problem.
To meet other customers’ requirements, the company began outsourcing some high-value components to subcontractors.
Sales went up.
But the additional outsourcing cost was eating into the profitability.
Once the team understood this connection, they reviewed the volume and value being handled through the critical machine and rationalised the production and outsourcing decisions.
The net profit improved from around 2% to 13%.
What is important here is not only the improvement in profit.
Until management started reviewing the P&L every month, the problem was not clearly visible. Operationally, everyone was working hard, and the company was producing and selling more.
The numbers helped the team connect what was happening across sales, capacity utilisation, outsourcing cost and profitability.
This is why I believe a P&L should not be seen merely as a financial statement.
For a founder or business head, it should help you understand what is really happening inside the business and where management attention is required.
What should an SME founder actually understand in a P&L?
You do not need to understand every accounting term to start using a P&L effectively.
As a founder or business head, you should first understand the basic flow of money through your business.
In simple terms, I look at the P&L in the following way:
Sales → Material cost → Manufacturing and operating expenses → Overheads → Operating profit → Interest, depreciation and tax → Net profit
Each part tells you something about the business.
Sales tells you how much business you have generated during the period.
Material cost helps you understand how much of your sales value is being consumed by raw material. Looking at material cost as a percentage of sales is particularly useful because changes can indicate issues with pricing, product mix, purchase cost, consumption, or inventory.
Manufacturing and operating expenses show what you spend to run the business. This could include manpower, power, subcontracting, consumables, freight and other operating costs.
Overheads help you understand the cost of running the organisation beyond direct manufacturing or delivery expenses.
Operating profit is one number I encourage business heads to watch closely. It gives you an indication of how effectively the core business is performing before interest, depreciation and tax.
Finally, net profit shows what remains after accounting for the other financial costs and tax provisions.
However, net profit should not be confused with cash flow. A profitable business can still face cash-flow pressure because money may be tied up in inventory, receivables, capital expenditures, or debt repayments.
The objective is not to become an expert in accounting.
The objective is to look at these numbers and start asking:
What changed? Why did it change? And what should we do about it?
Once a founder starts asking these questions every month, the P&L begins to shift from an accounting statement to a business management tool.
What should founders look for when reviewing P&L every month?
A monthly P&L review should not become another meeting where the finance person presents numbers and everyone listens.
The purpose is to understand what changed in the business and why.
When I review P&L with business heads, I normally encourage them to first look for variations rather than getting into every number.
Some simple questions can bring out useful insights:
- How have sales moved compared with the previous month?
- Has material cost moved in the same proportion as sales?
- Which operating expenses have changed significantly?
- Has the operating profit improved or reduced?
- If sales have increased, has profitability also improved?
- Is there any unusual increase in subcontracting, overtime, freight, scrap or other costs?
- Are there changes in customer or product mix affecting the margin?
- Is any one-time expense influencing the month’s profitability?
The important part is to go behind the variation.
If subcontracting cost has increased, the discussion should not stop with the finance team explaining the number. We need to understand what happened in operations. Was there a capacity constraint? Did a machine go down? Was there a delivery pressure?
Similarly, if material cost has increased, the reason could be purchase price, consumption, scrap, product mix or even the way inventory has been accounted for.
This is where a P&L review becomes a cross-functional business review.
Finance brings the numbers. Operations, sales, purchase and other functions help explain what happened behind those numbers.
Over a period, this practice also improves the business acumen of the leadership team. People start understanding how their functional decisions finally influence the profitability of the business.
That, in my view, is the real purpose of reviewing P&L every month.
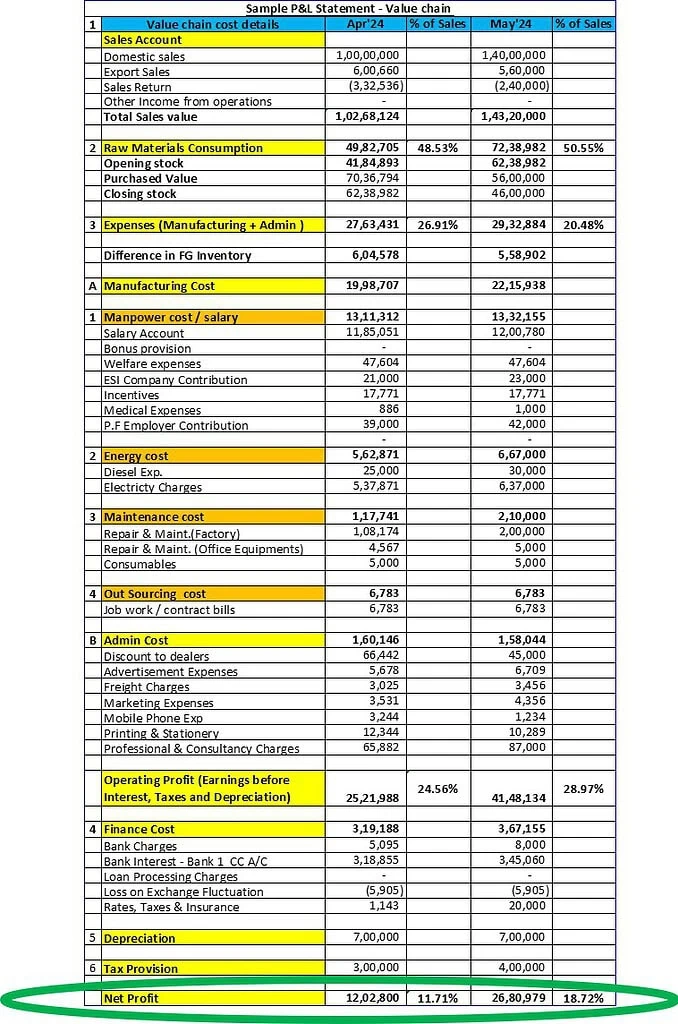
Sample P&L Statement format
Given below the sample P&L format as deigned by me and implemented in some of my client’s organization.
Even though one can get profit and loss statement in accounting software, say in TALLY, this format will have many advantages in terms of its simplicity.
- In this format, it is easy to compare the same cost element month on month.
- Also one can compare every cost element as a % of sales which will give relatable comparison to take right decisions.
Once you understand the concept behind the P&L Construct and how it needs to be interpreted, you can always modify or customize according to your organizational requirements.
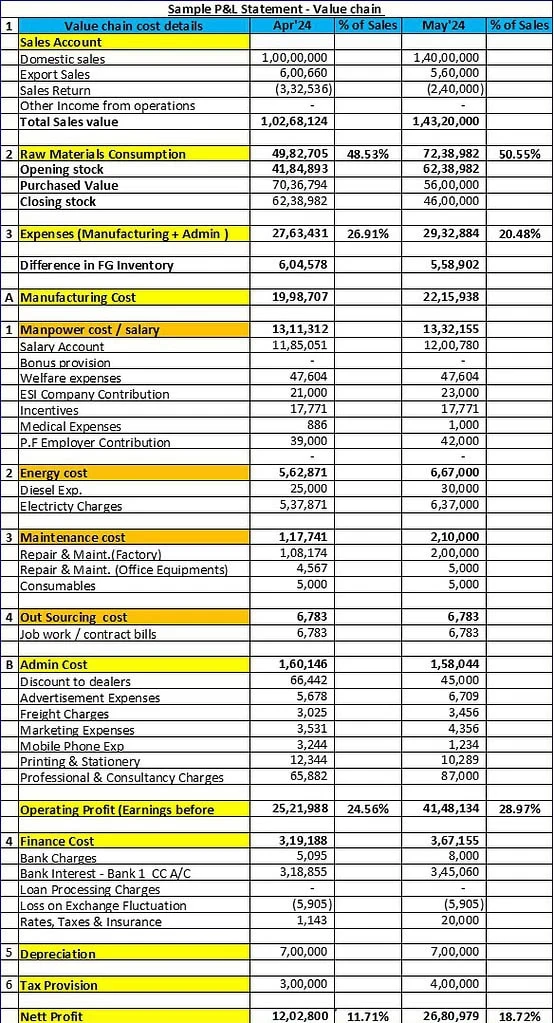
Key components of P&L Statement and its implications
There are many ways people make P&L format with different terminologies like COGS( cost of goods sold),EBITDA, OPERATING PROFIT, GROSS PROFIT, NET PROFIT and CONTRIBUTION etc.
However all of them leads to identify whether the business is healthy or not.
Given below the sample format i have developed and used in my clients.
To begin with, i suggest that you can understand the concept of P&L construct and you can use any format / terminology.
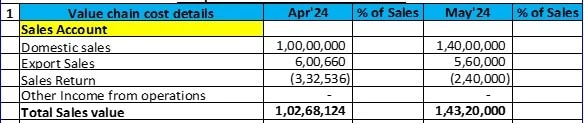
- Revenue Part :
This part includes all the sales or revenue accounting.
You may include Export / Domestic sales , Any sales returns can be deducted under this revenue part.
Sometime, you may get one time revenue other than operations .for eg, dividends income, scrap income etc , you can add under revenue part.
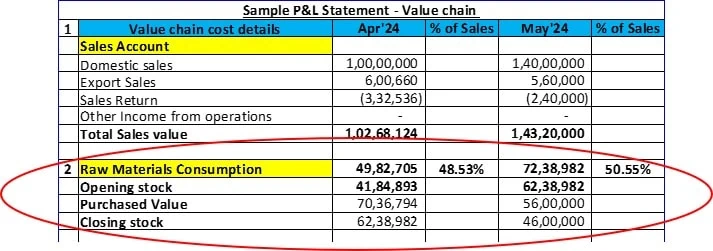
2. Raw Material Consumption:
This part includes RM consumption value as some CEO’s would like to see the RM consumption as % of sales.
This will be arrived from the opening inventory +purchased during the month -closing inventory from store /ERP data.
Tracking RM cost separately will give clarity with reference to sales.
Also once can understand the dynamics of closing / opening stock levels and accordingly can take decisions on purchasing.
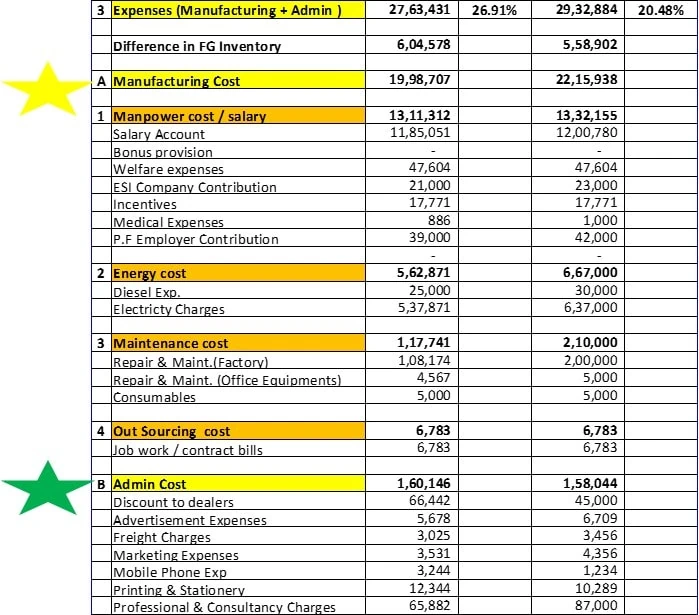
3.Expenses ( Both Manufacturing & Administration expenses):
This part includes expenses other than RM expenses. It includes in two parts, viz direct manufacturing expenses and indirect or administrative expenses.
Depending on the size of the company, some of the manpower expenses are allocated to manufacturing cost and some of the manpower cost to administrative or overhead expenses.
Those expenses can be compared to the sales in terms of Manufacturing Expenses as % of sales and Admin expenses as a % of sales.
The relative comparison against sales in every month will give a clear clarity on the expenses with reference to sales.
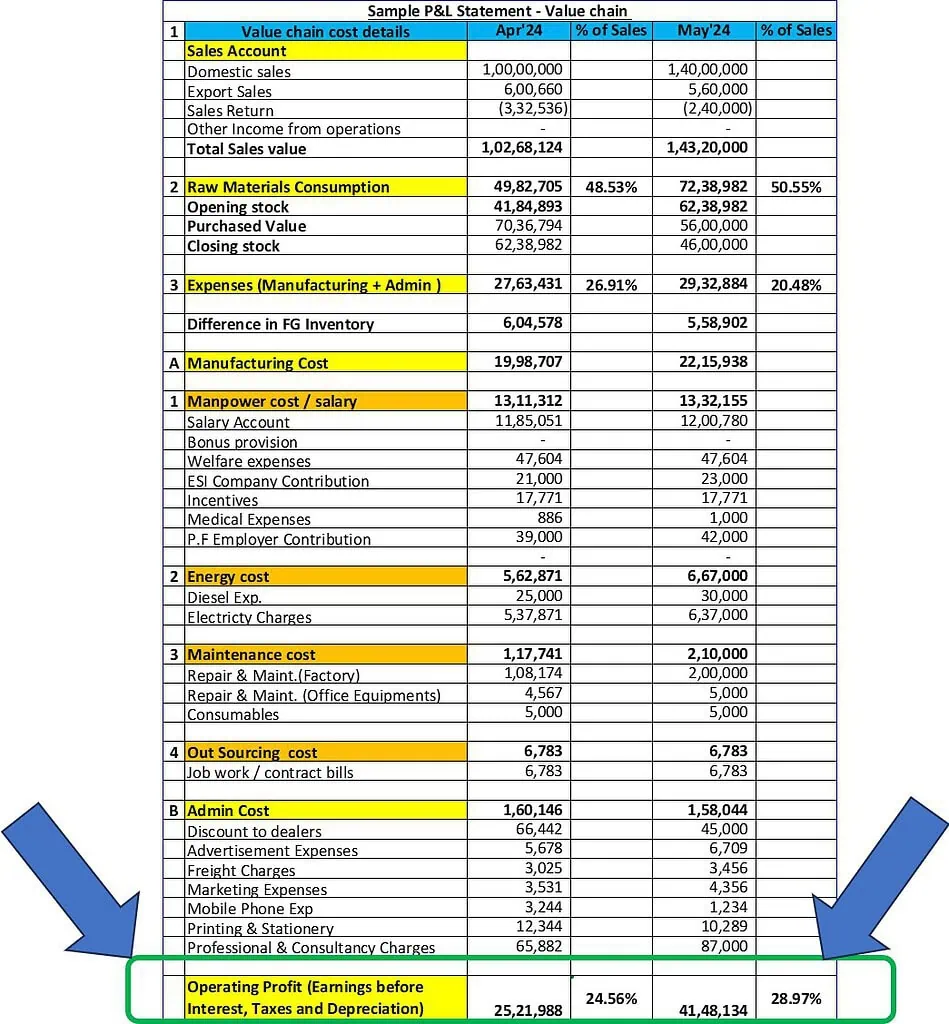
4.Operating profitability ( Before Finance, Depreciation and Tax expenses):
This part indicates the real operational effectiveness in terms of OPERATING PROFITABILITY.
This is arrived from the following formulae
Operating Profitability =Sales Revenue- Cost of Material – Cost of Expenses
Cost of expenses include direct and indirect expenses as mentioned above.
Operating profitability is alternatively termed as EBITDA. It stands for Earning before Interest, depreciation and amortization.
As a business head, you should see the effectiveness of your operations with this ” Operating profitability” measure.
This measure is also compared with sales as a % of sales.
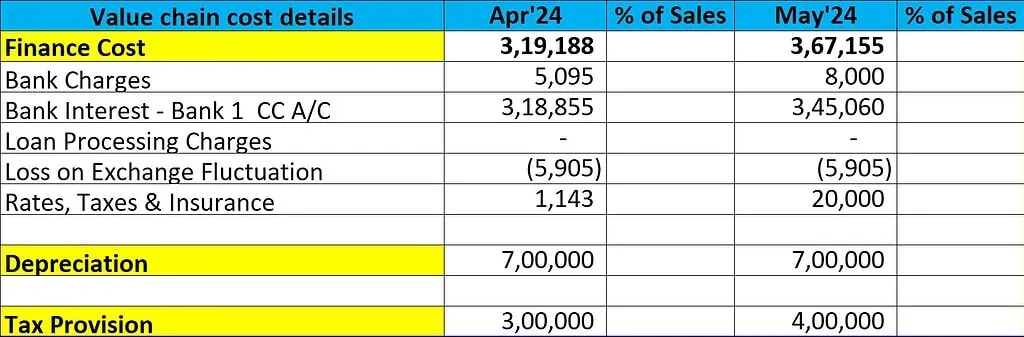
5.Interest / Depreciation and Income Tax provisions :
This part includes interest for the loan to banks and finance institutions and provision for depreciation.
Also, it includes provision for income tax based on the slab your company gets in.
By providing the provisions for all the above expenses, we are rightly arriving the net profitability.
5.Net profitability :
This part shows the overall money you take home after deducting all the expenses of running the business.
It is derived from the following formula
Net Profitability = Operating profitability- provision for interest, depreciation and income tax
This Net profitability is also compared with sales as a % of sales every month / quarter and this common scale will give a lot of insights for increase / decrease in net profitability.
What can a monthly P&L review reveal about your business?
One of the best management practices that most smart CEOs or business heads use monthly is reviewing the P&L (Profit and Loss) statement and key figures. Some organisations habitually review the P&L before the 10th of every month, which supports other organisational disciplines such as on-time accounting, bill collection, and settlement.
Benefits of conducting P&L analysis every month:
- As a business head, it allows you to understand the business profitability, either positive or negative, in the month, giving you more time to take corrective measures in the following months.
- Conducting P&L analysis every month provides insight into your profitable product mix. For example, in one of my client organisations, the team had a higher sales turnover than the previous month, but the operating margin was lower. Upon analysing the expenses, there wasn’t much variance between months. However, further analysis of the product mix revealed that the profit margin was low even though more of a particular product, say X, was produced and sold. This kind of analysis gives insight into your product mix, allowing you to optimise it accordingly.
- Analysing the P&L alongside the cost variance for each expense encourages the organisation’s cost consciousness. This allows you to take countermeasures to control costs. In many of my client organisations, reviewing the P&L every month has led to a shift in organisational culture towards cost consciousness.
What stops SMEs from reviewing P&L every month?
- Some people say the P&L statement may not reflect the real numbers due to variations in inventory accounting, tax provision, and depreciation.
Yes, the monthly P&L statement is notional and only indicative of your operational performance. At the year-end, with all requirements, your auditor will prepare the correct P&L, including accounting principles. This monthly P&L gives you an instant picture of your business performance so that you can take timely action.
Regarding inventory accounting, it will eventually become normalized when done regularly every month. You need to ensure that you use a standard format and input/output mechanism with the same source. For example, if you use TALLY software, use the same source and format/assumptions to prepare a P&L statement every month.
- Lack of discipline in accounting all the bills on time and preparing a P&L statement on time.
In my experience, this discipline starts with the business head. Once the leadership begins reviewing P&L consistently every month, the supporting accounting discipline also starts improving.
The point is, reviewing P&L analysis is a prime responsibility of the business head and should be done every month to take corrective action on business performance on time!
Founder diagnostic: Are you really using P&L to manage your business?
Before the next P&L review, ask yourself a few questions:
- Do I know whether our profitability improved or declined last month, and why?
- Can I identify the two or three costs that have changed significantly compared with sales?
- Do I understand which products, customers or business mix are improving or diluting our profitability?
- When a major cost changes, do we connect the number with what actually happened in sales, operations, purchase or delivery?
- Does our P&L review lead to specific business decisions and actions?
- Can my key functional heads understand how their decisions affect the business’s profitability?
If most of these questions are difficult to answer, the issue may not be the availability of financial data.
The opportunity is to make the P&L a more active part of your business management.
A simple P&L, reviewed consistently and discussed with the right questions, can gradually change how a founder and the leadership team view the business.
Why is understanding P&L an important business acumen for founders?
Understanding P&L is not only a finance capability.
For a founder or business head, it is part of business acumen.
As the business grows, you need to understand how decisions taken across different functions finally influence business performance.
A sales decision can change the product mix and margin.
An operations decision can influence productivity, overtime or subcontracting cost.
A purchase decision can affect material cost and inventory.
A capacity decision can influence delivery, outsourcing and profitability.
A people decision can increase cost today but may be necessary to build capability for tomorrow.
The P&L helps a business head connect many of these decisions with their financial impact.
This is one of the reasons I have included business acumen as an important capability for founders and business heads in my Profitable Growth Capability Framework (PGCF).
As the organisation grows, a founder cannot remain focused only on the function in which he or she has the strongest expertise. The ability to understand the business as a whole becomes increasingly important.
Regularly reviewing the P&L is one practical way to develop that capability.